Book a call →

The Askéon method · Umberto Callegari

Value is created in operations. Technology is the most underrated lever.

AIFI data for 2019–2024 on 64 deals say one thing: 71% of the value created in Italian SMEs comes from operational levers, and below €50 million in revenue the share rises to 86%. Financial leverage destroys value. This is the method we use to bring technology and AI into the P&L.

What the data say

The end of the financial-leverage era.

The study by the AIFI Research Office with BIP Corporate Finance & Strategy broke down the value created in 64 exits completed between 2019 and 2024 by 23 Italian investors, with an average holding period of five years. The result is a structural break: the two operational components, revenue growth and margins, account for 71% of the value. Debt leverage, for years the declared engine of returns, contributes negatively.

In companies with less than €50 million in revenue at entry, 64% of the sample, the operational share rises to 86%. This is the perimeter we work in: the companies where transformation is worth most are those with revenue of €5 million and above.

Anyone buying an Italian SME and counting on debt and rising multiples will not make the numbers work. The gain has to be created inside the company, operationally. And in this new era, technology and AI are the single most underrated, and most poorly implemented, lever in the Italian market.

Breakdown of value created · Italian private equity 2019–2024

Revenue growth
57%
EBITDA margin improvement
14%
Multiple arbitrage
40%
Financial leverage (negative contribution)
−11%

Source: AIFI + BIP Corporate Finance & Strategy, “Private Equity e Creazione di Valore”, September 2025. 64 deals, 23 investors, average holding period 5 years.

71%

of the value created comes from operational levers: revenue growth and margins

AIFI + BIP 2025, full sample

86%

the same share in SMEs below €50 million in revenue at entry

AIFI + BIP 2025, SME sub-sample

−11%

the contribution of financial leverage to value created: negative for the first time

AIFI + BIP 2025

64%

of the sample is SMEs below €50 million: the Askéon perimeter

AIFI + BIP 2025, distribution by revenue

Does it apply to your company too? We look at it on your financial statements, in a call.

Inside the companies

What value-creating funds actually do. And what nobody measures yet.

The interviews with 17 funds collected by AIFI map the operational anatomy of transformation. The levers converge on seven recurring areas. Only one is cited by all of them and not yet measured by any: AI.

  • 01
    Professional managementCFO hired or replaced, a team with a corporate background, incentive plans aligned with value creation.
  • 02
    Advanced reportingStructured monthly reporting, operational dashboards, strategy and control committees: “standard practice”, AIFI writes.
  • 03
    ERP, CRM, business intelligenceAlmost every fund cites advanced management systems as the first area of intervention after entry: a precondition for scaling.
  • 04
    Processes and supply chainSupply chain redesign, automation, lean manufacturing. Cited by 14 funds out of 17.
  • 05
    AcquisitionsTwo thirds of the 64 companies made at least one add-on acquisition during the holding period.
  • 06
    Cybersecurity and cloudA security assessment as the first activity after the acquisition, especially in SMEs exposed to digital.
  • 07
    AI and emerging technologiesAll 17 funds cite it as a transformative area. None of them yet maps it to comparable P&L KPIs.

Operational levers cited by the 17 funds interviewed · % of funds

Professional management and CFO
17/17
Advanced reporting
17/17
AI as a strategic lever
17/17
ERP, CRM, IT
16/17
Process digitalisation
14/17
Acquisitions
14/17
Cybersecurity and cloud
11/17

Source: our analysis of the AIFI + BIP 2025 interviews. In blue, the only lever cited by all the funds and not yet measured in the P&L.

Implementing AI in a company without first reading it as an economic system burns capital. The point is not which technology you use. It is where you act, why, and in which line of the P&L you book the result. It is a CFO’s exercise, not a CIO’s. This space, between a strategic importance everyone recognises and a method that does not yet exist, is exactly where we work.

The method

Five steps, one set of accounts. The owners decide at every checkpoint.

The method we apply, in Askéon Consulting as in our selective investments, turns this asymmetry into five steps. It is not a generic transformation plan: each step has a measurable result, and you can stop after any of them.

  1. 01

    Diagnosis

    5 weeks

    We start from the financial statements and the business, before touching any technology. A single assessment of processes and infrastructure, for AI and for security: which processes consume margin, which decisions are driven by data and which by habit, where the human factor is the bottleneck.

    Result: the levers quantified in euros of EBITDA and the use cases ranked by impact, cost and readiness.

  2. 02

    Plan

    6 weeks

    A 36-month roadmap with timing, costs, business case and the first hundred days, over three horizons: margin, then revenue, then new business models. The information base comes first: a unified P&L, with ERP, tax and sales data integrated. No complex AI before the foundations.

    Result: what to do, in what order, with which resources and what expected return.

  3. 03

    Technology and execution

    8–12 weeks per project

    One use case at a time in production. Each area has a sponsor in the company, milestones and P&L metrics tracked every month. AI is the operating arm; the P&L is the pilot. No platform to sell, no commissions from vendors.

    Result: a redesigned process, technology chosen in the client’s interest, a measured KPI.

  4. 04

    People

    ongoing

    Role-based training and internal champions who carry the change forward. Continuous training on AI and cybersecurity, as the AI Act (art. 4) requires of every organisation using AI and, for entities in scope, NIS2.

    Result: an organisation that knows how to use what it has bought, and documents it.

  5. 05

    Value

    12–24 months

    Documenting the operational gains and positioning the company as a technology-enabled business, towards banks, partners, industrial and financial buyers, and heirs.

    Result: EBITDA and multiple ready for an investor, or for the next generation.

Thirty-six disciplined months. No shortcuts, no AI on its own, no IT project without a sponsor in the P&L.

We start with the Diagnosis: five weeks, with no commitment to the next steps.

What real transformation returns

In five years the companies more than doubled. Without leverage.

The AIFI data show the median trajectory between the fund’s entry and exit across the 64 deals. These are not the numbers of those who used debt: financial leverage stayed contained, from 1.52 to 1.31 times EBITDA. They are the numbers of those who transformed the companies from within, and they measure what it is worth, for a business, to do in three years the operational work the method describes. It holds for those who sell, for those who hand over and for those who stay.

+114%

median revenue, from €38.4 million to €82.2 million

AIFI + BIP 2025, entry vs exit

+117%

median EBITDA, from €6.3 million to €13.7 million; margin from 15.6% to 17.2%

AIFI + BIP 2025

+1.9

points of median EV/EBITDA multiple, from 7.0x to 8.9x: the re-rating is earned by transforming

AIFI + BIP 2025

+190%

median enterprise value, from €42.4 million to €122.8 million

AIFI + BIP 2025

Same revenue, a different company

Enterprise value=EBITDASteps 1–3×multipleSteps 4–5

The first three steps raise EBITDA. The last two raise the multiple, because governed processes, trained people and demonstrable data reduce the risk seen by banks, buyers and heirs. The work on the multiple is done before the transaction, not during it.

Entry and exit, median of the 64 deals

Revenue at entry, €38.4m
38
Revenue at exit, €82.2m
82
Enterprise value at entry, €42.4m
42
Enterprise value at exit, €122.8m
123

Source: AIFI + BIP 2025. Median employees from 165 to 300; revenue CAGR 18.9%; average MOIC 3.7x, average IRR 30.4%, over a five-year holding period.

Generational succession

A million companies will change hands. The method is the same, the stakes are higher.

It is not a projection, it is arithmetic: 315,000 business owners are over 70, those under 40 are 11.3% and their share falls every year. 80% of entrepreneurs have thought about it; more than half have done nothing concrete. Only 31% of family businesses survive the first handover, 15% reach the third generation, only 3% go beyond. These percentages have not changed in twenty years, despite conferences, family pacts and practical guides.

The problem is not only the successor. It is the absence of numbers. Below €30 million in revenue, the filed financial statements are written for the tax authority, not for those who have to value, finance or buy the company: they do not show EBITDA, the real net financial position, customer concentration or the cash cycle. And in 70% of larger family businesses the leadership is entirely family-run, in 81% of smaller ones above €20 million: when the founder leaves, skills, relationships and often the relationship with the bank leave too.

There is, however, a figure almost nobody reads. Family businesses that completed the handover between 2013 and 2022 did better in the following three years than those that did not change leadership: revenue +1.1 points a year, investment in fixed assets +3.6 points, ROE +1.3 points, and less debt relative to EBITDA. A planned handover is not a risk: it is the largest untapped source of value in Italian family capitalism.

Family businesses that survive the handover · by generation

To the second generation
31%
To the third generation
15%
Beyond the third generation
3%

Entirely family-run leadership · family businesses above €20m, 2023

Smaller companies
81%
Larger companies
70%
Leadership open to a non-family member
24%

Sources: AIDAF (survival by generation); AUB Observatory XVI, 2025, 2023 data (AIDAF-EY Chair at Bocconi, UniCredit, AIDAF); CNA, April 2026, 2,000 entrepreneurs; Unioncamere-InfoCamere 2025. Askéon analysis.

1m

Italian companies that will have to change leadership in the coming years

Confindustria 2024, CNA 2026

315,000

business owners over 70; those under 40 are 11.3%

Unioncamere-InfoCamere, June 2025

50%

of entrepreneurs know they have the problem and have not yet done anything

CNA, April 2026

+3.6

extra points a year of investment in the three years after the handover, compared with those that did not change leadership

AUB Observatory XVI, Bocconi, 2025

The same five steps, read by those who have to hand over

Generational succession is not prepared with feelings. It is prepared with numbers. Read the Note →   On LaMiaFinanza, in Italian →

Do you need to hand over in the next five years? Let’s start from the numbers, in a call.

The Askéon thesis

Three numbers, one position.

71% / 86%

Operational levers

If you cannot transform, the numbers do not work.

71% of the value created in Italian SMEs comes from revenue and margins. Below €50 million, 86%. Financial leverage subtracts.

Value is made inside the company, not in the structure of the deal.

17 / 0

AI

Everyone cites it. Nobody measures it.

17 funds out of 17 name AI as a strategic lever. None yet describes a method measurable in the P&L.

This is the asymmetry we work in: AI as the operating arm, the P&L as the pilot.

7.0× → 8.9×

Multiple

The re-rating is earned, not awaited.

Almost two extra points of multiple between entry and exit, in the AIFI median. They come from processes, people and data, before the transaction.

A technology-enabled company is worth more to banks, buyers and heirs.

Executing this transformation requires a profile the Italian market rarely produces: operators who have run industrial P&Ls, with real enterprise technology capability, able to translate technology strategy into the CFO’s language. A consultancy that does not stop at slides: it goes into the company, brings AI into the processes and makes it work in the months that follow.

Askéon Capital was born at this intersection. Not a fund: operators. Askéon Consulting as our main business, selective investments when operations, vision and technology justify them. Technology as a value multiplier.

We don’t sell transformation. We execute it.

Intelligo ergo sum · understanding the context is the condition, not the result

Want the same exercise on your financial statements? Let’s start with a call.

The author

Written by someone who applies it.
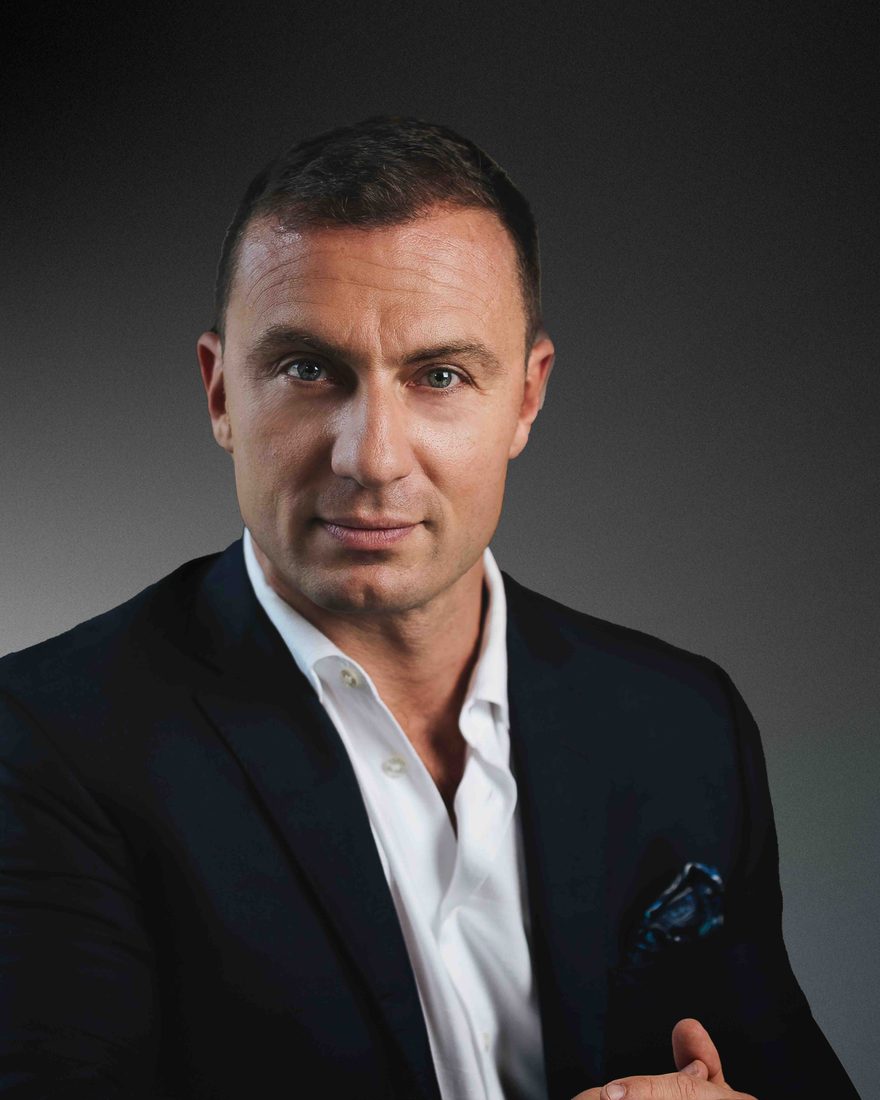
Umberto Callegari, Founding Partner of Askéon Capital

Umberto Callegari

Founding Partner · Askéon Capital

Twenty years as an operator: at Microsoft he led advisory and transformation for Western Europe, EMEA and worldwide, with more than 300 senior professionals; before that Accenture, Monitor Deloitte and Octo Telematics. Today a partner and director in Italian SMEs, and the author of the Askéon Notes.

The method described on this page is the same one we apply in Askéon Consulting engagements and in the companies where we are shareholders.

   LinkedIn →    The Askéon Notes →    The companies where we are shareholders →

Sources

AIFI, Research Office, with BIP Corporate Finance & Strategy, “Private Equity e Creazione di Valore”, 24 ORE Cultura, September 2025. Sample: 64 exits completed between 2019 and 2024 by 23 Italian private equity investors; interviews with 17 funds (Aksìa, Alto Partners, Ambienta, Argos Wityu, Aurora Growth Capital, B4 Investimenti, Consilium, DeA Capital Alternative Funds, Fondo Italiano d’Investimento, Gradiente, H.I.G. Capital, IGI Private Equity, Mindful Capital, and others). The percentages by lever are our analysis of the interviews.

Let’s start from your financial statements.

In a call we work out where AI is really worth it for your company, and whether it makes sense to work together.

Book a call →

or write to us: info@askeon.capital

Book a call →